SBA 504 equipment financing lets a business buy long-lived machinery with about 10% down and a fixed rate for 10 years. The loan is split between a bank and a Certified Development Company (CDC), a nonprofit lender that the U.S. Small Business Administration (SBA) authorizes to deliver the program. At CDC New England, the published rate for our Equipment 10-Year Fixed loan was 6.58% when we last updated our site in September 2026. Below you will find how the structure works, what equipment fits, what it costs and how to apply.
Cdcnewengland
cdcnewengland.com
Finance Equipment With a Fixed Rate
CDC New England provides SBA 504 financing for business equipment, with a 10% down payment requirement and fixed rates for up to 25 years.
TL;DR
Table of Contents
What SBA 504 equipment financing is
The SBA describes the 504 program as long-term, fixed-rate financing for major fixed assets that promote business growth and job creation. The maximum 504 loan amount the SBA lists is $5.5 million. Fixed assets means two things in practice: commercial real estate and heavy, long-lived equipment.
The word “fixed” matters twice. The asset is a durable one, and the rate does not change for the life of the loan. For a manufacturer, fabricator, processor or similar operation, that means you can lock the cost of a production line instead of watching a variable rate move your monthly payment.
How the project is financed: the 50/40/10 split
Under 13 CFR 120.801, a typical 504 project has three parts:
Here is a worked example. You buy a $1,000,000 production machine.
SourceShareAmountYour contribution10%$100,000CDC debenture40%$400,000Third-party lender50%$500,000
The fixed-rate debenture carries the largest long-term portion of the project, which is why the program keeps cash in your business. For a deeper look at who pays and when, see our guide to the 50/40/10 SBA 504 structure.
Two details from SBA Form 2450, the eligibility information required for a 504 submission, help you plan:
If you are buying equipment as part of acquiring another company, a vendor loan in a business purchase is a separate seller-financing structure that can sit next to the financing described here.
What equipment qualifies
The SBA states that 504 can finance long-term machinery and equipment with at least 10 years of remaining useful life, including project-related AI-supported manufacturing equipment. That 10-year test is the main filter. It is also why the equipment loan term is 10 years: the debt is matched to the life of the asset.
What that means for common questions:
If the equipment is going into a building you are also buying or improving, a single 504 project can cover both. Our guide to 10% down 504 loans for manufacturing equipment walks through that case.
Rates, terms and fees
The SBA says 504 maturities are 10, 20 and 25 years, and that the rates are pegged to an increment above the current 10-year Treasury market rate. Equipment projects use the 10-year term. The 20- and 25-year terms are generally used for real estate.
Our published rates as of September 2026:
ProgramTermFixed rateEquipment 10-Year Fixed10 years6.58%Real Estate 20-Year Fixed20 years6.73%Real Estate 25-Year Fixed25 years6.77%
These are the figures published on our site in September 2026. Because the underlying benchmark is the 10-year Treasury market rate, the debenture rate changes as that market moves, so use our current rate sheet or a quote for planning, not an old article. Our page on 10, 20 or 25 year SBA 504 terms explains how term length affects your payment.
On fees, the SBA describes total charges of approximately 3% of the debt, which may be financed. Financing the fees means you do not need to pay them from your own cash at closing. Ask for a full closing cost estimate for your project, since the fee total depends on the debenture amount.
A quick payment comparison to run
For equipment, the usual alternative is a conventional equipment loan or lease. Compare these points on every quote:
Our article on the 10 year rule for 504 versus equipment loans lays out the comparison, and our 504 versus conventional article does the same for 10% down and 25 years.
Who qualifies
The SBA’s 504 page says that to qualify, a business must be operating, for-profit, located in the United States, small under SBA size requirements and not an ineligible business type. The same page names general standards: qualified management expertise, a feasible business plan, good character and the ability to repay.
In practice, lenders want to see:
Our 504 loan requirements for New England page covers the checklist in more detail.
How to apply, step by step
Under 13 CFR 120.801, you apply through a CDC serving the area where the project is located. For equipment in Massachusetts, Rhode Island, Vermont, New Hampshire or Connecticut, that is us.
Timelines depend on how complete your package is and how quickly the equipment vendor and bank respond, so ask us for the current timeline for your project.
Refinancing equipment debt with a 504 loan
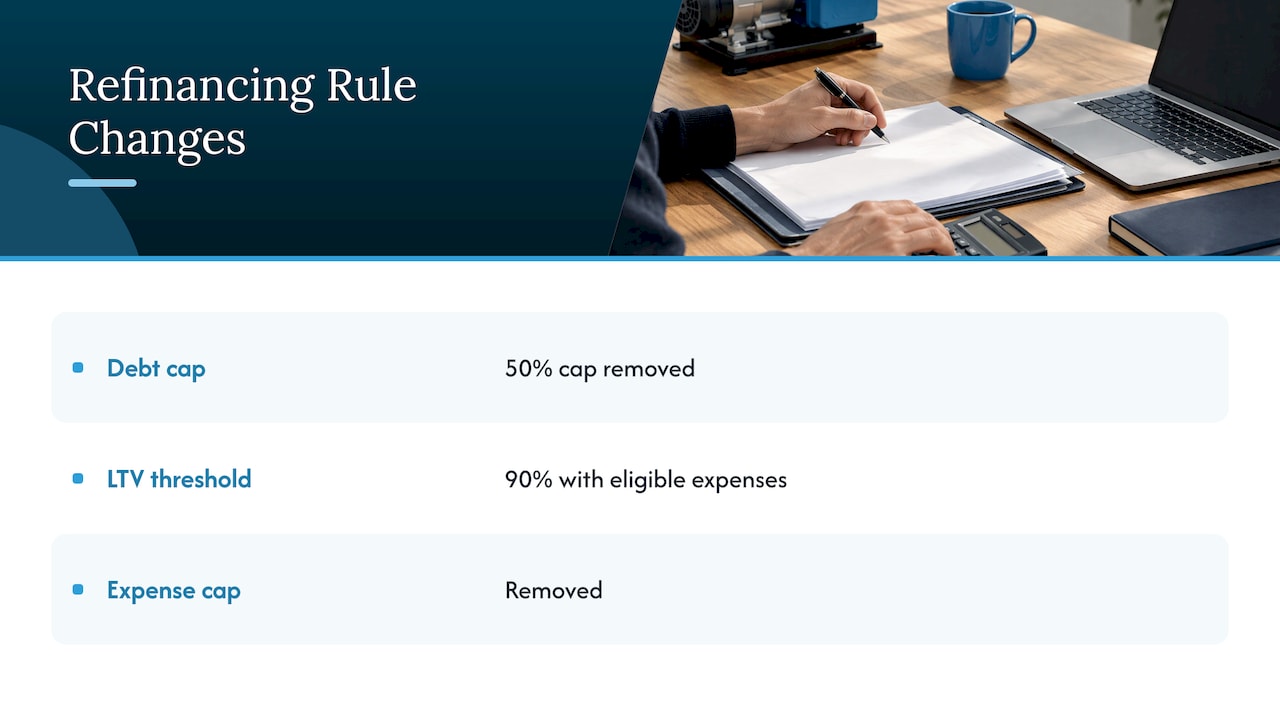
If you already own equipment financed with higher-cost or shorter-term debt, a 504 refinance can be part of the plan, as long as the debt meets the SBA’s qualified-debt conditions. The SBA’s October 1, 2024 Federal Register rule, effective November 15, 2024, removed the 50% cap on 504 debt refinancing without expansion. The same rule raised the loan-to-value threshold to 90% for refinancing-without-expansion projects that include eligible business expenses and removed the cap on those expenses.
Whether your particular equipment debt qualifies depends on its terms and age, so send us the note and payment history. You can read more on our SBA 504 Refinance Program page, and our guide to refinancing with expansion covers the case where you add new equipment at the same time.
Veterans and down payment help
If you are a veteran or the spouse of one, our VetLoan Advantage Program is designed for you. The program carries a 1.0% processing fee. If the 10% contribution is the obstacle, our Down Payment Assistance Program is built for that gap.
Our perspective
We have spent more than 70 years financing New England businesses, and we have invested more than $2.3 billion in the region. What we keep coming back to is simple: equipment should be paid for over the years it produces.
A fixed 10-year rate on a machine with at least 10 years of useful life lets you plan margins on every part it makes. A 10% contribution leaves the rest of your cash for payroll, materials and the next opportunity. That is the reason we believe the 504 is the strongest way for a qualifying business to buy durable equipment.
Because we are a local CDC with Premier Certified status, we work with your bank and your equipment vendor from the first conversation. We also offer a veteran program and down payment assistance, so owners who thought the up-front cash was out of reach can see a path to yes.
PHENYX
Start your equipment project with us
Our Equipment 10-Year Fixed loan was published at 6.58% in September 2026, with a 10% contribution and a structure built around your equipment’s useful life. Send us your vendor quote and we will outline the financing for your project.
Explore the Equipment 10-Year Fixed program and current rates on our site, or contact us to talk through your purchase.
FAQ
What is the minimum down payment on an SBA 504 equipment loan?
The borrower contribution is at least 10% of the project cost under 13 CFR 120.801. Per SBA Form 2450, it may be cash or project property. If you borrow it, the loan must be subordinate to the 504 liens.
Can I use a 504 loan for working capital or inventory?
No. The SBA says 504 proceeds cannot go to working capital or inventory. The program funds fixed assets. By keeping your down payment low, though, it leaves more of your own cash available for those needs.
How long is the term for equipment financing?
Equipment projects use the 10-year term, while 20- and 25-year terms are generally for real estate. The SBA lists 10, 20 and 25 years as the 504 maturities. Our Equipment 10-Year Fixed rate was 6.58% as published in September 2026.
Do I apply with the SBA or with a lender?
You apply through a CDC that serves the area where the equipment will be located, per 13 CFR 120.801. The CDC works with the third-party lender that provides the first-lien portion. In New England, you can start with us.