The SBA 504 maximum loan is generally capped for most projects, with a higher limit available for qualifying manufacturers or energy-efficient projects, but that figure covers only the SBA-backed debenture portion, not your total project cost. As of July 4, 2026, borrowers can combine 7(a) and 504 financing for up to $10 million in total SBA-backed debt, opening the door to larger real estate and equipment deals than ever before.
TL;DR:
- The maximum SBA 504 loan amount is capped at $5.5 million, but certain manufacturing, energy, or renewable projects can qualify for higher limits.
- Starting July 2026, borrowers may combine up to $5 million through a 7(a) loan and $5.5 million through a 504 debenture, totaling up to $10 million in SBA-backed debt.
- Eligibility for the higher cap requires meeting specific owner-occupancy, citizenship, and beneficial ownership disclosure requirements, especially for foreign-owned businesses.
- The SBA’s funding structure allocates roughly 50% from a first mortgage, 40% from the debenture, and 10% from the borrower’s contribution, with terms up to 25 years on real estate.
- Reaching the maximum funding amount demands early preparation of documentation and close coordination between the borrower, lender, and CDC to ensure eligibility and optimal deal structuring.
Table of Contents
- SBA 504 Loan Limits: Standard Caps vs. Higher Project Thresholds
- What Changed in July 2026: Combining 7(a) and 504 for $10 Million
- Eligibility Rules That Determine Whether You Can Hit the Cap
- How the SBA Calculates Your Maximum: The Capital Stack Explained
- Repayment Terms and Rate Mechanics on Large 504 Debentures
- Applying for SBA 504 Financing Through a Certified Development Company
- CDC New England: Tools and Programs Built for Borrowers Chasing the Cap
- Should You Chase the Maximum SBA 504 Loan?
- Get Your SBA 504 Financing Structured for Maximum Impact
- Sources
- FAQ
SBA 504 Loan Limits: Standard Caps vs. Higher Project Thresholds
The debenture cap has been a baseline for years, still governing most 504 transactions. The SBA’s own program guidance confirms that figure while also flagging a slightly higher ceiling for specific project categories.
You qualify for the higher cap under a narrower set of circumstances than most borrowers assume. The exceptions generally include:
- Small manufacturers investing in facilities or equipment that meet SBA’s manufacturing definition
- Projects that reduce energy consumption by at least 10%
- Projects that generate renewable energy, such as solar or biomass installations
These SBA 504 loan limits apply strictly to the SBA-backed debenture, the third piece of the 504 capital stack. Your total project financing, once you add the participating lender’s first mortgage and your own contribution, routinely runs well past $5.5 million. Most deals get sized by what the project actually needs and whether it clears eligibility screens, not by pushing straight for the statutory ceiling.
What Changed in July 2026: Combining 7(a) and 504 for $10 Million
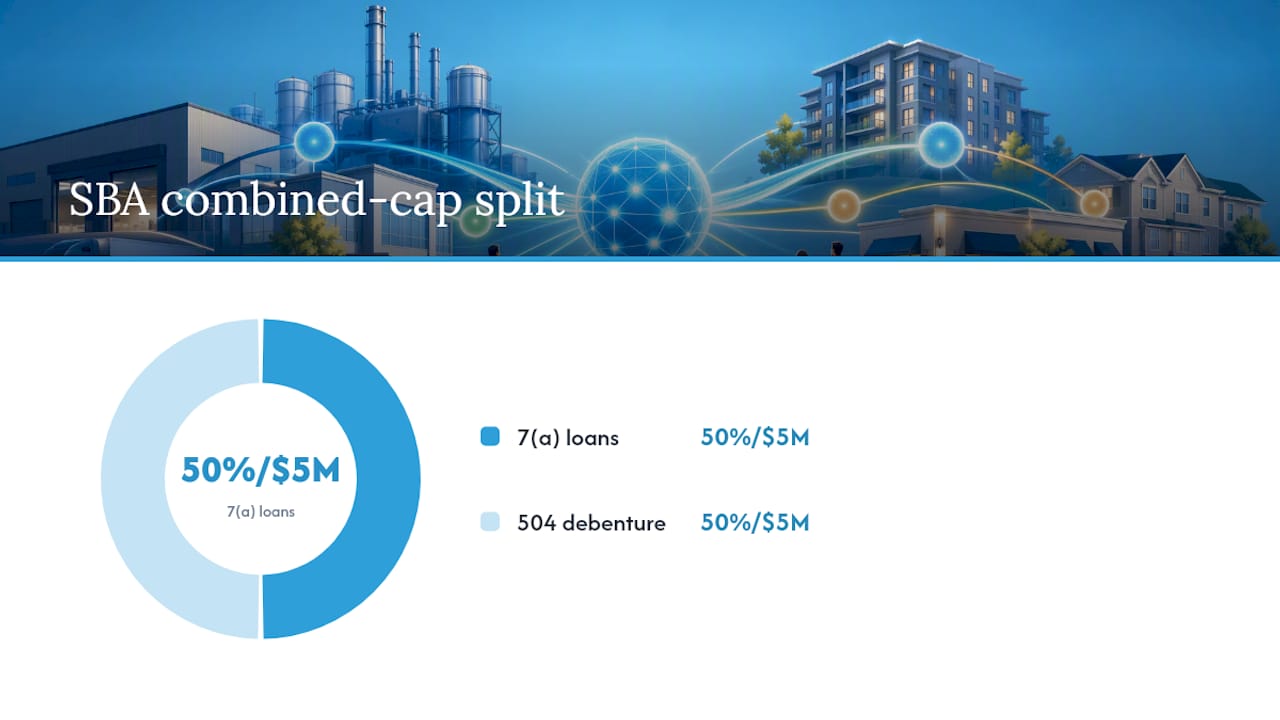
For years, borrowers treated 7(a) and 504 as separate financing lanes with separate limits. The SBA’s May 2026 announcement changed that by decoupling the cumulative caps, letting eligible borrowers stack both programs into one financing package worth up to $10 million in SBA-backed debt.
The mechanics work like this:
- Up to $5 million through a 7(a) loan, typically used for working capital, inventory, or business acquisition
- Up to $5 million (or $5.5 million for qualifying projects) through a 504 debenture for real estate or heavy equipment
The $10 million combined ceiling doubles what capital-intensive borrowers could previously access through SBA-backed channels in a single financing structure, according to the SBA’s press release.
Manufacturers and other equipment-heavy businesses stand to benefit the most, since they often need both operating cash and fixed-asset financing at the same time. Sequencing matters here. Lenders and Certified Development Companies generally expect the 7(a) loan to close first to preserve the combined-cap mechanism, so coordinate timing with both parties before you submit paperwork.
Eligibility Rules That Determine Whether You Can Hit the Cap
Reaching the maximum SBA 504 funding available to you depends on more than the dollar figures. Ownership, occupancy, and disclosure requirements factor into whether your application clears underwriting.
A procedural notice from the SBA clarified applicant ownership, citizenship, and residency requirements that affect who qualifies for both 7(a) and 504 loans. Key eligibility factors include:
- Owner-occupancy requirements differ between existing and new construction buildings
- Disclosure of beneficial owners holding a significant percentage of the business on SBA Form 1244
- Total beneficial ownership disclosure covering a majority share of the company
- Verified citizenship or lawful permanent residency status for principal owners
Massachusetts and Rhode Island borrowers with foreign ownership stakes should review these residency rules closely, since they can affect timeline and documentation even when the business itself is fully eligible.
Pro Tip: Gather your beneficial ownership documentation before you approach a CDC. Incomplete Form 1244 filings are one of the most common reasons 504 applications stall in underwriting.
How the SBA Calculates Your Maximum: The Capital Stack Explained
The SBA 504 structure splits every project into three layers, and understanding that split explains why “maximum SBA 504 funding” and “maximum project size” are two different numbers.
- A conventional lender covers roughly 50% of total project cost through a first mortgage on the property or equipment.
- The CDC-issued debenture covers roughly 40%, capped at $5 million or $5.5 million depending on project type. This is the portion the SBA guarantees.
- You contribute the remaining 10% as a down payment, lower than the 20 to 25% many conventional commercial loans require.
Manufacturer exceptions and projects using multiple 504 loans can shift this ratio, particularly when energy or green-building incentives apply. If you want to see how these percentages translate into real numbers for your project, CDC New England’s loan calculator lets you model the debenture, lender share, and your injection side by side.
Repayment Terms and Rate Mechanics on Large 504 Debentures
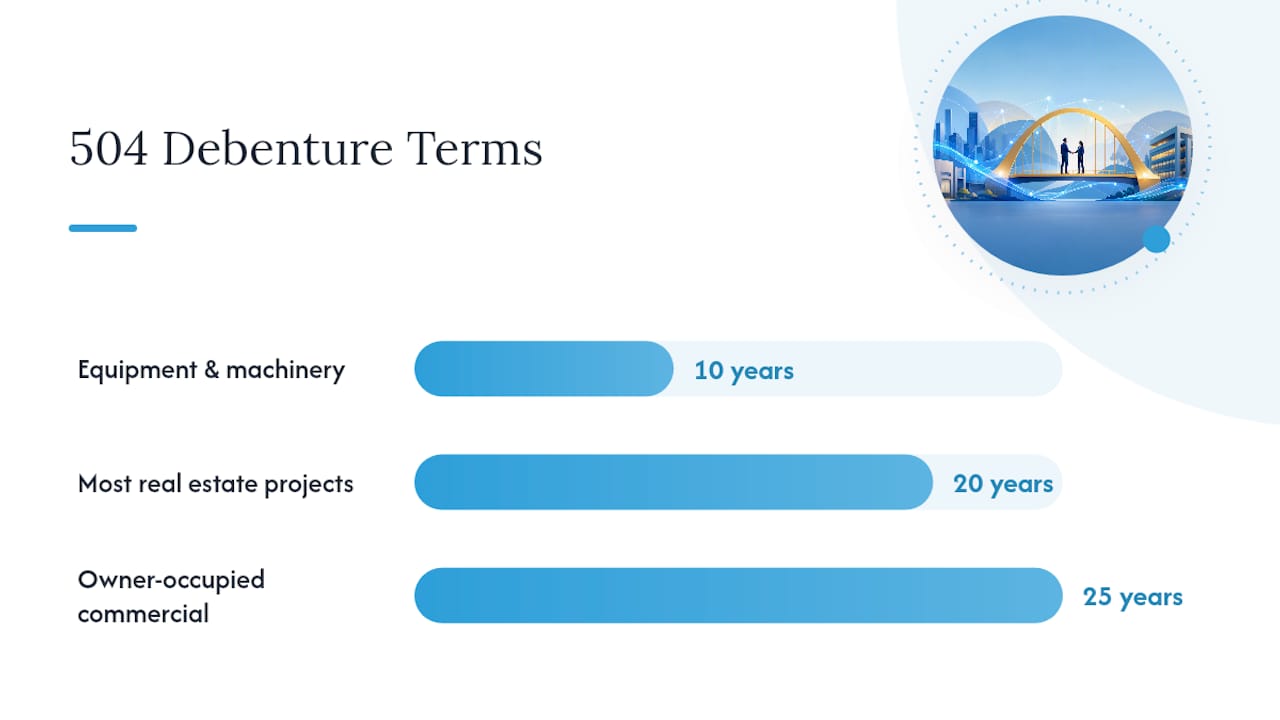
The 504 debenture portion carries a fixed rate for the life of the loan, which matters enormously when you’re financing at or near the cap. Terms typically run:
- 10 years for equipment and machinery
- 20 years for most real estate projects
- 25 years for owner-occupied commercial buildings
Amortization is fully self-liquidating, meaning there’s no balloon payment waiting at the end. The rate gets set at the time your debenture funds, based on an underlying Treasury benchmark plus program fees, so the number you see quoted today won’t necessarily match what you lock in at closing.
Before committing to a maximum-sized debenture, run the numbers with both the interest rate and closing fees included. Prepayment penalties on 504 debentures decline gradually but can still be significant in the early years, so factor that into your long-term cost projections.
Applying for SBA 504 Financing Through a Certified Development Company
Certified Development Companies originate and service every 504 loan, working alongside your conventional lender rather than replacing it. You can locate a CDC through the SBA’s directory or by contacting a regional lender directly.
Expect to prepare:
- SBA Form 1244 with complete beneficial ownership disclosure
- Two to three years of business financial statements and tax returns
- A detailed project cost estimate covering real estate, construction, or equipment
Timelines typically run several weeks to a few months from application to closing, though incomplete ownership documentation or unresolved occupancy questions are the most common causes of delay. CDC New England’s SBA 504 page walks New England borrowers through the process, and the loan calculator helps you estimate numbers before you ever submit paperwork.
CDC New England: Tools and Programs Built for Borrowers Chasing the Cap
Reaching a high SBA 504 funding package takes more than eligibility; it requires a CDC skilled in structuring the deal.
A certified development company may have extensive experience financing regional businesses, including commercial real estate and equipment purchases across New England states. A few tools matter directly for borrowers pursuing larger loan amounts:
- Down payment assistance that can lower the required injection, freeing up cash for other project costs
- Benefits for veteran and military-spouse-owned businesses through dedicated programs
- A loan calculator that models the debenture, lender share, and monthly payment for loan applicants
Contact a CDC early in your project planning. The earlier you start, the more room you have to structure financing that actually reaches the maximum your project needs.
Should You Chase the Maximum SBA 504 Loan?
The $10 million combined option is a real opportunity for capital-intensive businesses. Manufacturers and equipment-heavy operators finally have a path to fund working capital and fixed assets without choosing one over the other.
But bigger isn’t automatically better. Before pursuing the ceiling, assess your actual repayment capacity and operational readiness, and coordinate 7(a) and 504 timing closely with your lender and CDC. The math only works if your cash flow supports it.
— PHENYX
Get Your SBA 504 Financing Structured for Maximum Impact
CDC New England gives you a direct path to the SBA 504 program without the guesswork of piecing together lender relationships on your own.
If you’re a veteran or military spouse, the VetLoan Advantage program adds further benefits on top of standard 504 terms. Not every business qualifies for the higher caps or the combined $10 million financing structure, and a CDC will provide guidance based on eligibility rather than promising unattainable funding amounts. Visit the SBA 504 loan page to request a free eligibility check, or run your numbers through the loan calculator before your first call.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- SBA Doubles Cumulative 7(a) and 504 Loan Limit to $10 Million
- Procedural notice — revised applicant ownership/citizenship/residency requirements
FAQ
What is the maximum loan term for an SBA 504 loan?
The debenture portion of an SBA 504 loan runs for 10, 20, or 25 years depending on whether you’re financing equipment or real estate, with full amortization and no balloon payment.
Can I get a $100,000 SBA loan?
Yes. The 504 program has no statutory minimum, and CDCs regularly fund smaller projects, though most lenders look for a project size where the fixed costs of underwriting still make sense relative to the loan amount.
How do I get a $5 million SBA loan?
You’d work with a Certified Development Company to structure a 504 debenture at the standard $5 million cap, or combine it with a $5 million 7(a) loan under the new rule to access up to $10 million in combined SBA-backed financing.
How hard is it to get an SBA 504 loan?
Approval depends heavily on documentation completeness, particularly beneficial ownership disclosure on SBA Form 1244 and meeting owner-occupancy thresholds, more than on the size of the loan itself. Businesses with organized financials and a clear project scope tend to move through underwriting faster than those without.