New Hampshire small business owners have plenty of financing options when it comes time to buy a building or invest in major equipment. But not all small business loans are built the same. For owner-occupied commercial real estate, the SBA 504 loan consistently outperforms conventional financing on the three things that matter most: down payment, rate stability, and monthly payment.
This guide breaks down exactly why, with current numbers, so you can decide which path makes sense for your business in Manchester, Nashua, Portsmouth, Concord, or anywhere else in the Granite State.
Quick Summary
- The SBA 504 loan typically requires a 10% down payment, compared to 20% to 25% for conventional commercial mortgages.
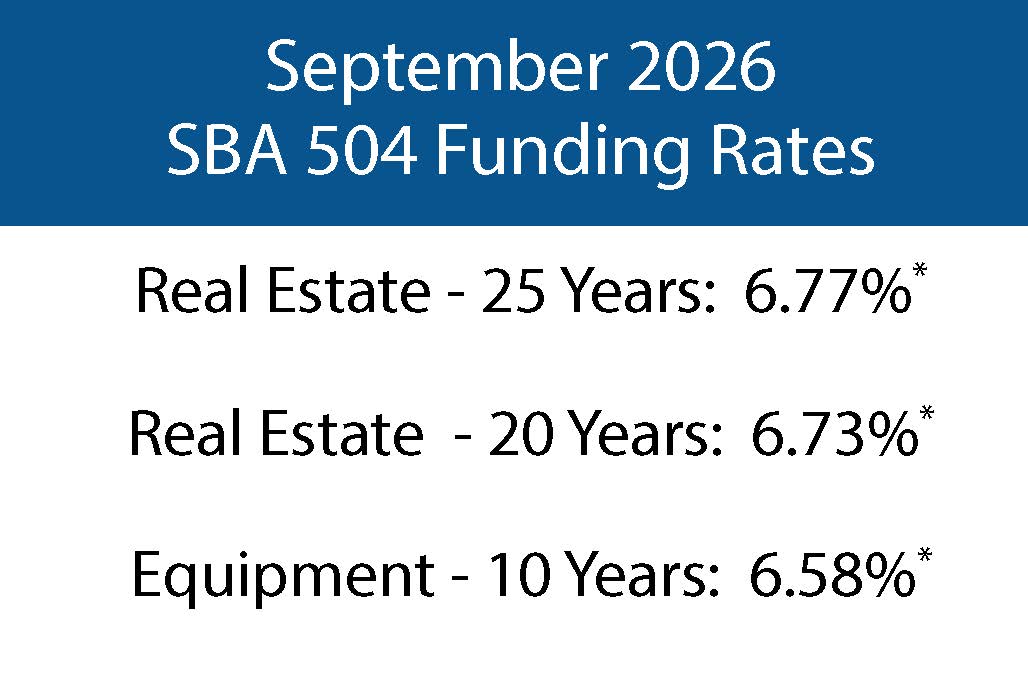
- As of May 2026, effective SBA 504 rates are 6.11% for 25-year terms, 6.16% for 20-year terms, and 5.88% for 10-year terms, including fees.
- The 504 rate is fixed for the entire term. Many conventional commercial loans reset every 5 years or carry balloon payments.
- New Hampshire manufacturers receive 504 rates roughly 25 basis points lower due to an SBA fee waiver for NAICS sectors 31 through 33.
- The SBA-backed portion can reach $5.5 million, supporting total projects well beyond that amount.
- Conventional loans still make sense in some cases, such as non-owner-occupied investment property, which the 504 program cannot finance.
- New Hampshire businesses apply through a Certified Development Company (CDC), which partners with a local bank or credit union.
What Is the SBA 504 Loan Program?
The SBA 504 loan is a long-term, fixed-rate financing program for major fixed assets, most often owner-occupied commercial real estate. It is delivered through Certified Development Companies, nonprofit lenders certified and regulated by the SBA.
A 504 project splits into three parts. A bank or credit union provides a first mortgage for about 50% of the project cost. The CDC provides a second mortgage for up to 40%, funded through an SBA-guaranteed debenture. The borrower contributes the remaining 10%.
A conventional commercial mortgage, by contrast, comes from a single lender that carries the full risk. That difference in structure explains nearly every advantage the 504 holds.
SBA 504 vs. Conventional Financing: The Side-by-Side
Here is how the two options compare for a typical New Hampshire owner-occupied real estate purchase:
Feature
SBA 504 Loan
Conventional Commercial Loan
Down payment
Typically 10%
Typically 20% to 25%
Rate on CDC portion
Fixed for full term
Often resets every 5 years
Term length
10, 20, or 25 years
Often 5 to 10 year terms with balloons
Amortization
Fully amortizing
Frequently 20 to 25 years with a balloon
Maximum SBA portion
$5.5 million
Varies by lender
Eligible property
Owner-occupied only
Owner-occupied or investment
Advantage 1: A 10% Down Payment Keeps Cash in Your Business
The most immediate difference is the equity injection. On a $1.5 million building purchase in Nashua, a conventional lender asking for 25% down needs $375,000 from you at closing. A 504 structure typically needs $150,000.
That $225,000 difference is not just a closing-table number. It is inventory, payroll, equipment, and a cash cushion that stays inside your business. For growing companies, preserving working capital is often the deciding factor.
Startups and special-purpose properties, such as hotels or self-storage facilities, may require 15% to 20% down under the 504 program. Even then, the requirement usually beats the conventional alternative for the same property type.
Advantage 2: A Fixed Rate That Never Resets
Most conventional commercial mortgages in New England are not fixed for their full amortization. A common structure is a 20-year or 25-year amortization with a rate that resets every 5 years, or a balloon payment that forces a refinance.
Business owners who took conventional loans at historic lows learned how much a reset can hurt when rates climbed. A payment that jumps hundreds or thousands of dollars per month is a real risk to plan around.
The CDC portion of a 504 loan removes that risk entirely. The rate set at funding is the rate for the life of the loan, whether that is 10, 20, or 25 years. Your bank prices the first mortgage separately, but with roughly 40% of your project locked at a fixed rate, your exposure to future rate movement shrinks dramatically.
Advantage 3: Competitive Rates, Especially for Manufacturers
SBA 504 rates are set nationally each month when the SBA sells debentures to investors. As of the May 2026 pricing, effective rates including all fees are:
- 25-year term: 6.11%
- 20-year term: 6.16%
- 10-year term: 5.88%
New Hampshire manufacturers do even better. Businesses with a primary NAICS code in sectors 31, 32, or 33 currently benefit from a waiver of the SBA annual service fee, bringing their effective rates down by roughly a quarter point, to 5.87% on a 25-year term as of June 2026. For a state with a deep manufacturing base, from precision machining along the Merrimack Valley to electronics and aerospace suppliers in the Seacoast region, that discount is worth knowing about.
These rates change monthly, so the rate that applies to your loan is the one in effect when your debenture funds.
Advantage 4: Longer, Fully Amortizing Terms
A 504 loan amortizes fully over its term. There is no balloon payment looming in year 5 or year 10, and no forced refinance at whatever rates happen to be at that moment. Combined with terms up to 25 years, full amortization keeps monthly payments lower and predictable from the first payment to the last.
When Conventional Financing Still Makes Sense
An honest comparison cuts both ways. Conventional financing is the better or only fit when:
- The property is an investment. The 504 program requires your business to occupy at least 51% of an existing building or 60% of new construction. Pure investment real estate is not eligible.
- You need maximum speed and minimal process. A single conventional lender can sometimes close faster on a simple deal, though an experienced CDC keeps the 504 timeline competitive.
- You need working capital or inventory financing. The 504 program funds fixed assets only. For working capital, an SBA 7(a) loan or conventional line of credit is the right tool.
- Your business exceeds SBA size standards. Companies with a tangible net worth above $20 million or average net income above $6.5 million do not qualify for the 504 program.
For most New Hampshire small businesses buying their own building, though, none of these exceptions apply, and the 504 structure wins on the numbers.
Who Qualifies for an SBA 504 Loan in New Hampshire?
The eligibility requirements are broader than many owners assume. To qualify, your business must:
- Operate as a for-profit company in the United States
- Have a tangible net worth of less than $20 million
- Have an average net income of less than $6.5 million after federal income taxes for the two preceding years
- Occupy at least 51% of an existing building, or 60% of new construction
- Use the funds for eligible fixed assets such as land, buildings, improvements, or long-term equipment
- Demonstrate sound credit, repayment ability, and qualified management
The overwhelming majority of New Hampshire small businesses fall within these limits.
How to Apply for an SBA 504 Loan in New Hampshire
The application process runs through a Certified Development Company, which handles the SBA requirements so you do not have to navigate them alone. Here is the process step by step:
- Contact a CDC that serves New Hampshire. Start the conversation early, even before you have a property under contract.
- Define your project. Outline what you plan to buy or build and the estimated total cost.
- Gather financials. Plan on two to three years of business tax returns, current interim statements, personal financial statements for owners of 20% or more, and a debt schedule.
- Pair with a lender. Your existing New Hampshire bank or credit union can provide the first mortgage, or the CDC can connect you with experienced 504 lending partners.
- Underwriting and SBA approval. The bank underwrites its portion while the CDC underwrites and submits the SBA piece.
- Close and fund. The bank typically funds interim financing at closing, and the SBA debenture funds at the fixed rate set in that month's pricing.
A Note for New Hampshire Lenders
The 504 structure works in a lender's favor too. The bank's first mortgage sits at roughly 50% loan-to-value, a strong collateral position that helps with concentration limits and credit policy. Partnering with a CDC also gives lenders a way to serve solid borrowers whose available down payment will not support a conventional structure. If you have a New Hampshire borrower who fits this profile, a CDC can pre-screen and structure the deal quickly.
Conclusion: The Bottom Line for New Hampshire Businesses
For owner-occupied commercial real estate, the SBA 504 loan beats conventional financing where it counts. You keep more cash at closing with a 10% down payment, you lock a fixed rate for up to 25 years with no resets or balloons, and as of June 2026 those fixed rates sit near 6%, with manufacturers paying even less.
Conventional financing still has its place, especially for investment property and working capital. But if your New Hampshire business is ready to own its building, the 504 deserves a serious look before you sign conventional loan documents.
CDC New England has helped small businesses and lending partners across New England put the 504 program to work for decades. If you want to compare the numbers for your specific project, reach out at www.cdcnewengland.com/contact-us for a no-obligation conversation.
Frequently Asked Questions
Is an SBA 504 loan better than a conventional loan?
For owner-occupied commercial real estate, the SBA 504 loan usually wins on down payment and rate stability. It requires about 10% down versus 20% to 25% for conventional loans, and its rate is fixed for the full term. Conventional loans are better for investment property and working capital, which the 504 cannot finance.
What are SBA 504 loan rates in New Hampshire right now?
SBA 504 rates are set nationally each month. As of the May 2026 debenture pricing, effective rates including fees are 6.11% for 25-year terms, 6.16% for 20-year terms, and 5.88% for 10-year terms. New Hampshire manufacturers qualify for rates roughly 25 basis points lower.
How much can a New Hampshire small business borrow with a 504 loan?
The SBA-backed portion can reach $5 million for most projects and $5.5 million for small manufacturers and certain energy projects. Because that covers only about 40% of a project, total project sizes can exceed $10 million when combined with the bank first mortgage and borrower contribution.
Can I use an SBA 504 loan for equipment instead of real estate?
Yes. The 504 program finances long-term machinery and equipment with a remaining useful life of at least 10 years. This makes it a strong fit for New Hampshire manufacturers investing in production equipment, often at the same favorable fixed rates as real estate projects.
What credit score do I need for an SBA 504 loan?
The SBA does not set a minimum credit score for the 504 program. CDCs and partner banks look at the complete picture, including business cash flow, credit history, and management experience. Strong credit helps, but a solid business with moderate credit can still qualify.
Loans are subject to credit approval and SBA eligibility requirements. Rates shown reflect June 2026 SBA 504 debenture pricing and are subject to change monthly.