A Certified Development Company (CDC) is an SBA-certified nonprofit that packages and services 504 loans, letting small businesses buy real estate or equipment with as little as 10% down. Fixed rates run 10, 20, or 25 years. Start by checking the SBA’s list of Certified Development Companies in your state.
TL;DR:
- A CDC allocates up to 40% of a project through SBA-guaranteed debentures, with fixed rates ranging from 10 to 25 years and a minimum 10% borrower equity.
- Eligibility requires small business size, specific asset use like real estate or equipment, and occupying at least 51% of the property, excluding nonprofits and passive investors.
- Vetting a CDC involves checking its recent loan volume, delegated authority status, and fee transparency, with references from past SBA deals; vague responses indicate red flags.
- Recent rule changes have made refinancing easier, allowing businesses operating for over two years to refinance up to 90% of property value or 85% with eligible expenses.
- The 504 loan is best suited for long-term assets like owner-occupied real estate or heavy equipment, with nearly 9,700 loans approved annually, making it a popular option for substantial investments.
Table of Contents
- What Is a Certified Development Company, Exactly?
- How Does the SBA 504 Loan Structure Work?
- Who Qualifies for a CDC-Backed 504 Loan?
- How Do You Find and Vet the Right CDC?
- Can You Refinance Debt Through a 504 Loan?
- How Does the SBA Certify and Oversee CDCs?
- What Working With CDC New England Looks Like
- When Does a 504 Loan Actually Make Strategic Sense?
- Ready to Finance Your Next Property or Equipment Purchase?
- Sources
- FAQ
What Is a Certified Development Company, Exactly?
A CDC is a private, nonprofit corporation certified by the U.S. Small Business Administration to package, process, close, and service 504 loans within a defined area of operations. Every CDC exists to promote economic development in its region, which is why terms like “job creation” and “public policy goals” show up throughout SBA program materials. This isn’t a side business for these organizations. It’s their entire mandate.
To earn certification, a CDC must meet governance and financial requirements outlined in the SBA’s CDC Certification Guide, including board composition rules and proof of the financial ability to operate. Most CDCs offer:
- Loan packaging and underwriting support for 504 applications
- Closing coordination between the borrower, bank, and SBA
- Long-term loan servicing for the life of the debenture
- Regional economic development programs tied to job creation
The National Association of Development Companies (NADCO) and the SBA’s own directories are worth bookmarking. Both function as trust signals, since not every organization calling itself a “development company” carries actual SBA certification.
How Does the SBA 504 Loan Structure Work?
The 504 program splits financing three ways, and understanding that split explains almost everything else about how these loans behave. Your CDC covers up to 40% through a debenture that carries a 100% SBA guarantee, secured by a junior lien.
By the numbers: A standard 504 deal breaks down as roughly 50% bank financing, up to 40% CDC debenture, and a minimum 10% borrower equity, with terms available at 10, 20, or 25 years fixed.
That structure changes for riskier profiles. The tradeoff for that lien subordination is a below-market fixed rate locked for the life of the loan, which is a rare feature in commercial lending. Businesses weighing this structure against a conventional loan often preserve more working capital by keeping their cash out of the down payment.
Who Qualifies for a CDC-Backed 504 Loan?
Eligibility hinges on business size, use of funds, and occupancy. The SBA sets tangible net worth and average net income thresholds that most operating small businesses clear without issue, but it’s worth confirming before you invest time in an application.
- Size test: Your business generally must fall under SBA size standards, with tangible net worth and average net income limits set at the federal level.
- Use of funds: Eligible projects include land, ground-up construction, existing building purchases, major equipment, and certain energy-efficiency retrofits.
- Occupancy rule: You must occupy at least 51% of an existing building (60% for new construction) since 504 financing is not built for pure investment or rental properties.
- Excluded uses: Nonprofit organizations, speculative developments, and passive real estate holding don’t qualify.
- Documentation: Applications run through SBA Form 1244, alongside financial statements, business tax returns, and a project cost breakdown your CDC will help assemble.
How Do You Find and Vet the Right CDC?
Start with the SBA’s official CDC directory rather than a general web search, since anyone can claim 504 expertise without holding certification. Cross-reference candidates against the NADCO membership list for an added layer of verification.
Once you have a shortlist, dig into specifics:
- How many 504 loans has this CDC closed in the past year, and in what project categories?
- Does it hold delegated authority, such as PCLP or ALP status, which speeds up closing?
- What’s its typical timeline from application to funding?
- How are fees structured, and are they disclosed upfront in writing?
Pro Tip: Ask a prospective CDC for two SBA-related references from closed deals in your industry. A CDC confident in its track record will hand these over without hesitation. One that hedges or gets vague about fees and timelines is a red flag worth taking seriously.
Vague answers about processing time or reluctance to name past SBA District Office contacts should send you looking elsewhere.
Can You Refinance Debt Through a 504 Loan?
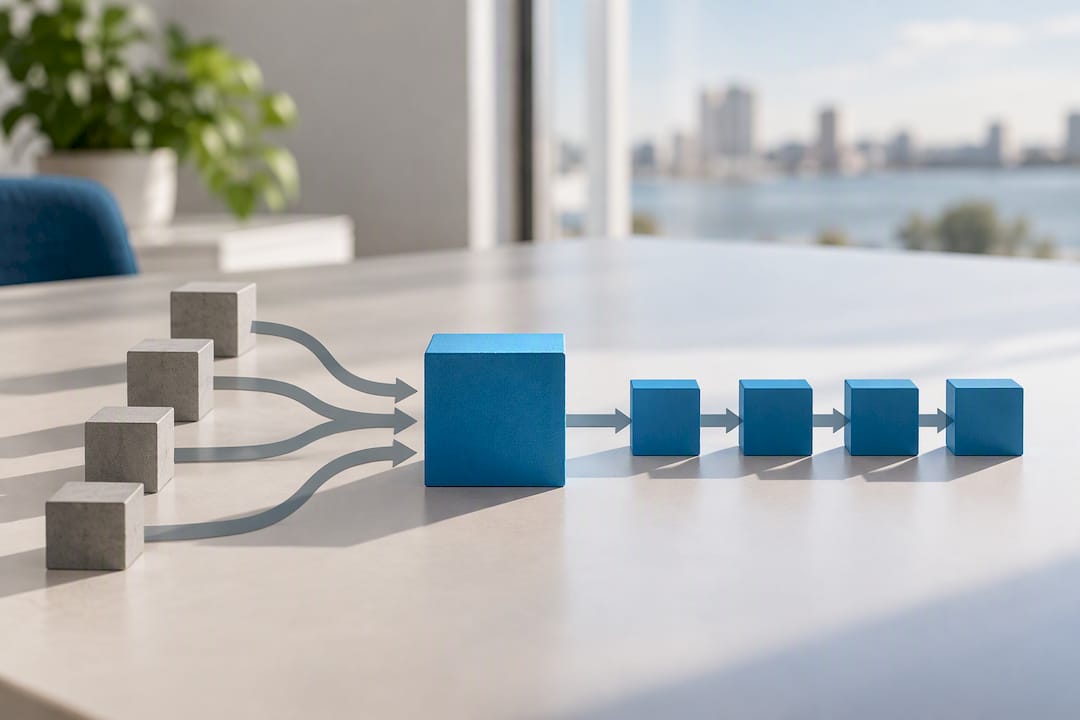
Yes. Recent rule changes loosened restrictions on 504 debt refinancing, and eligibility now generally requires that your business has operated for at least two years, with the existing debt current for the prior 12 months. Under updated SBA guidance, borrowers can refinance up to 90% of appraised property value, or 85% when rolling in eligible business expenses.
Beyond straight refinancing, many CDCs run specialty programs worth asking about:
- Veteran-focused loan tracks with reduced fees or faster processing
- Down payment assistance for borrowers short on the 10% equity requirement
- Bridge support for businesses restructuring existing commercial debt
Procedural updates matter here too. SOP 50 10 7.1, effective November 15, 2023, changed several processing requirements CDCs and borrowers should confirm are current before submitting paperwork.
How Does the SBA Certify and Oversee CDCs?
Certification isn’t a one-time formality. CDCs file SBA Form 1246 and must demonstrate ongoing financial ability to operate under federal regulations, plus meet board and staffing standards tied to their certified area of operations.
Oversight continues well past initial approval:
- Annual reporting keeps the SBA informed of loan volume and portfolio health.
- Risk-based reviews evaluate underwriting consistency across a CDC’s loan book.
- Delegated authorities like ALP, PCLP, and ACL shift closing responsibility to CDCs that have proven a strong track record.
GAO reporting found that oversight has historically centered on underwriting standards and job-creation reporting, and it recommended clearer guidance so CDCs report job numbers consistently. That oversight exists because CDC performance varies meaningfully from one organization to the next, and inconsistent underwriting creates real risk for borrowers, not just for the SBA’s guarantee fund.
What Working With CDC New England Looks Like
CDC New England has invested more than $2.3 billion in regional businesses across Massachusetts, Rhode Island, Vermont, New Hampshire, and Connecticut. Borrowers work with a CDC that combines that regional track record with several borrower-focused features:
- 10% down payment requirement on standard 504 projects
- Fixed rates for up to 25 years on real estate, with 10-year terms available for equipment
- A VetLoan Advantage Program built for veteran and spouse-owned businesses
- A Down Payment Assistance Program for borrowers who need help clearing the equity bar
If your business already has a bank relationship and a property or equipment purchase in mind, reviewing the 504 basics is a reasonable next step before reaching out for a specific quote.
When Does a 504 Loan Actually Make Strategic Sense?
A 504 loan earns its keep when you’re financing a real asset you’ll hold for years, an owner-occupied building or heavy equipment, where locking a fixed rate for two decades matters more than speed. The SBA approved nearly 9,700 of these loans in a single recent year, which tells you this isn’t a niche product. If you just need short-term working capital or you’re buying something under $150,000, a 504 loan’s closing timeline probably isn’t worth it. For anything more complex than that, a conversation with a CDC or your local SBA District Office beats guessing.
— PHENYX
Ready to Finance Your Next Property or Equipment Purchase?
This CDC is an alternative to stretching your cash reserves thin on a conventional commercial loan.
Beyond the standard 504 structure, CDC New England runs a VetLoan Advantage Program for veteran and spouse-owned businesses and a Down Payment Assistance Program for borrowers who need extra help meeting equity requirements. If you’re carrying existing commercial debt, the SBA 504 Refinance Program may restructure it into a fixed, predictable payment. As always, confirm your eligibility details with a CDC or SBA District Office before signing anything. To see current rates and start a conversation about your project, visit the SBA 504 loan page and request a quote.
Sources
- SBA lenders | U.S. Small Business Administration
- CDC Certification Guide | U.S. Small Business Administration
- Actions needed to ensure planned improvements address key requirements of the Development Company (504) Loan Program | U.S. GAO
FAQ
What Are Certified Development Companies?
Certified Development Companies are nonprofit organizations certified by the SBA to package, process, and service 504 loans for small businesses buying real estate or equipment. Each CDC operates within a defined regional territory and works alongside a bank and the borrower in the three-party 504 structure.
Do You Pay Back an SBA Loan?
Yes, an SBA 504 loan is a fully repaid loan, not a grant, with fixed monthly payments over 10, 20, or 25 years depending on the asset financed. The CDC services the loan for its full term, and missing payments carries the same consequences as any commercial debt.
Who Is the Largest SBA Lender?
SBA lender rankings shift year to year and vary by loan program, so no single lender holds a permanent title. For 504 loans specifically, borrowers should compare regional CDCs like Cdcnewengland based on local approval volume and delegated authority rather than national lending totals.
What Is the Payment on a $1,000,000 Business Loan?
Monthly payments depend heavily on the rate, term, and structure, since a 504 loan splits the amount across a bank portion and a CDC debenture with different terms. Because Cdcnewengland’s current rates change with market conditions, use the SBA 504 loan calculator for an estimate based on today’s figures.
How Long Does It Take to Close a 504 Loan?
Closing timelines vary by CDC, project complexity, and whether the CDC holds delegated authority such as PCLP or ALP status. Ask any CDC for its typical timeline in writing during your first conversation, since a vague answer here is often a sign of bigger process problems ahead.